Which situation fits you?
Every retirement roadmap I build starts from the client’s actual situation, not a generic template. Pick the page closest to yours:
- Singles or single-income households
- Couples and dual-income households
- Business owners
- Medical professionals
- Malaysians with investment properties
- Malaysians with mortgages
- Malaysians with too many insurance policies
- Malaysians earning Singapore dollars
- Malaysians working in the Middle East
- Malaysians working in the US or Europe
Not sure? Start with a confidential assessment and I’ll tell you which roadmap applies.
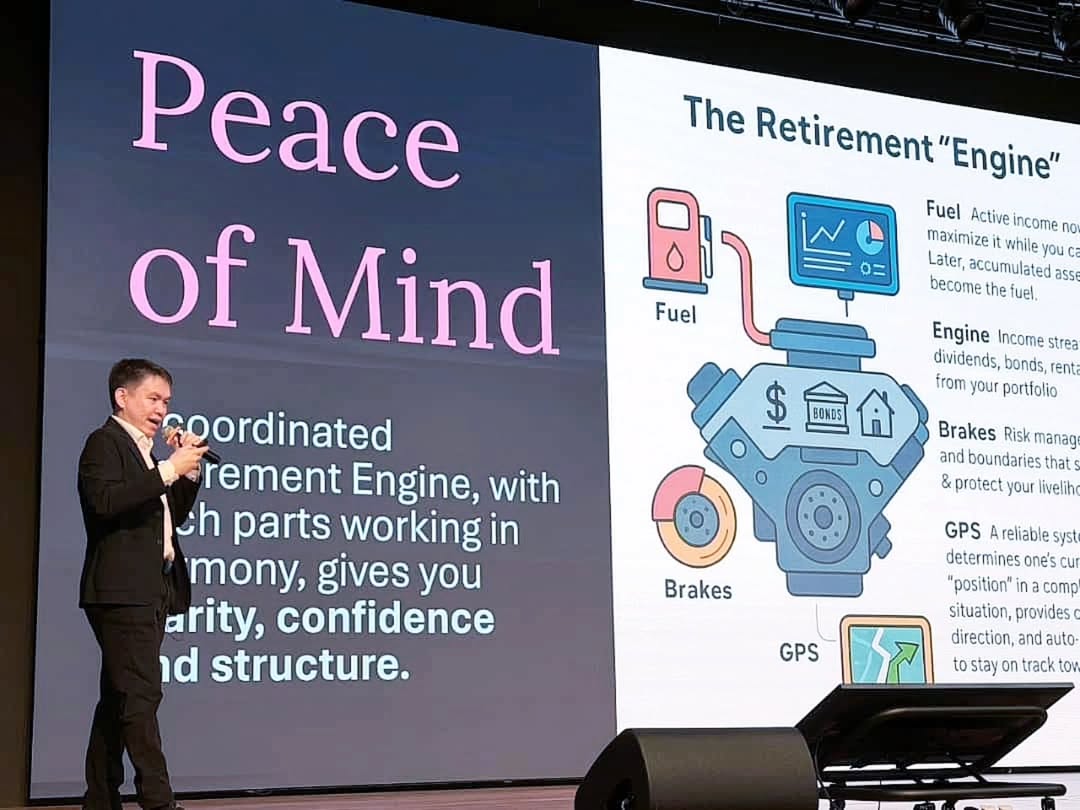
I am CF Lieu, My work includes being a licensed advisor for my retirement financial advisory clients and trainer for financial institutions and banks since 2012.
Retirement Financial Advisor for Malaysians with Overseas Investment Property
A flat in London, a house in Melbourne, a condominium in Singapore – Malaysians who worked or studied abroad often come home with property they kept, or they buy overseas from Malaysia as a hedge against the ringgit. Either way, the property arrives in the retirement plan with a set of complications that a local property never has: it earns in one currency, is taxed in another jurisdiction, is managed from thousands of kilometres away, and its role in a Malaysian retirement is rarely defined.
A retirement financial advisor for Malaysians with overseas property helps answer the question that usually goes unasked: does this asset actually earn its place in a retirement that will be lived, and spent, in ringgit?
Why overseas property needs a different planning process
The first difference is currency. An overseas property is a large, illiquid bet on an exchange rate. When the foreign currency strengthens against the ringgit, the owner feels wealthy; when it weakens, or when the retirement is funded in ringgit while the asset sits in pounds or dollars, the mismatch works against the plan. The property’s contribution to retirement income has to be modelled in the currency the retiree will spend, with realistic exchange-rate scenarios.
The second is tax. Foreign rental income, foreign capital gains, and the treatment of foreign-sourced income when remitted to Malaysia each carry rules that change – and that interact with your tax residency in the year you return. This is exactly the terrain covered in my guides for Malaysians returning from overseas work and on reorganising foreign accounts and investments after returning.
The third is management. A property that is a small inconvenience while you live in the same city becomes a persistent drain – agents, repairs, tenant turnover, compliance – when managed remotely in retirement, and the costs of that management erode a yield that may already be thin.
What a financial advisor for overseas property owners should help clarify
The first is the honest net yield in ringgit terms, after foreign tax, management, currency conversion costs and vacancy. This number is frequently much smaller than the owner’s mental figure.
The second is the role of the asset. Is it a retirement income source, a currency hedge, a home for future use, or a legacy asset for children studying abroad? Each is a legitimate role, but they call for different decisions – and an asset trying to fill all four usually fills none well.
The third is the sell-or-keep decision and its timing. Selling overseas property involves foreign capital gains rules, currency timing, and repatriation planning; the difference between a well-sequenced sale and a hurried one can be substantial. The complete guide for Malaysians working overseas and returning home covers the broader coordination problem.
The decisions that need coordination
- Currency exposure in the whole plan. How much of the retirement balance sheet is in foreign currency, and is that level deliberate or accidental?
- Foreign tax and Malaysian remittance timing. When rental income or sale proceeds come home matters, and it should be planned around your residency status, not left to chance.
- Debt on the overseas asset. A foreign mortgage funded by foreign rental is one thing; a foreign mortgage that a ringgit retiree must service is another.
- Local versus overseas retirement assets. Overseas property, EPF, Malaysian property and investments need to be seen as one portfolio – not two separate lives.
- Succession across borders. Property in another jurisdiction may fall under that jurisdiction’s succession rules. That is worth understanding while it can still be arranged.
A better way to evaluate your current position
The AI-powered scenario analysis on this page models your overseas property alongside everything else – in ringgit, with exchange-rate, tax and yield scenarios you can adjust – using the same engine I use with advisory clients. It answers the practical questions: what does this property contribute to retirement income at today’s rates, what happens if the currency moves 15% against you, and how does the plan change if the property is sold in year 3 versus kept for 20 years?
A typical situation I see
A Malaysian engineer who spent twelve years in the UK, returned home at 44, and kept a two-bedroom flat in Manchester “as a hedge.” Gross rent is £1,250 a month; after agent fees, UK tax, insurance, service charge and periodic voids, the net is closer to £700 – and by the time it is converted and lands in Malaysia, it funds perhaps a tenth of the household’s intended retirement spending. Meanwhile the flat represents about 30% of the family’s net worth, all in one currency, one city and one asset. The property is not a bad investment; it is an unexamined one. The decision the model surfaces is whether that 30% does more for retirement as a UK flat or as a diversified, income-producing portfolio in the currency the retirement will actually be spent in – and the answer depends on assumptions the family had never been asked to state.
Frequently asked questions
Should I sell my overseas property when I return to Malaysia?
Not automatically. The right answer depends on the net yield in ringgit, the property’s share of your total net worth, the foreign tax on sale, and what the proceeds would do instead. What matters is that the decision is modelled rather than deferred.
How is overseas rental income taxed for a Malaysian resident?
It depends on the source country’s rules, any tax treaty with Malaysia, and Malaysia’s treatment of foreign-sourced income at the time it is remitted. These rules change, which is why the timing of remittances should be planned around your residency status.
Is overseas property a good currency hedge for a Malaysian retirement?
It hedges, but crudely – the exposure is large, illiquid and undiversified. A deliberate allocation to foreign-currency investments can achieve the same hedge with far more flexibility and far less concentration.
How to choose an advisor without adding another conflict
Overseas property owners get advice from two sides: foreign agents who want the asset kept and managed, and local product sellers who want the proceeds invested with them. Choose an advisor who is licensed in Malaysia, paid by you alone, and equally comfortable recommending that you keep, sell or restructure. My guide on choosing a certified financial planner in Malaysia explains what to verify.