Which situation fits you?
Every retirement roadmap I build starts from the client’s actual situation, not a generic template. Pick the page closest to yours:
- Singles or single-income households
- Couples and dual-income households
- Business owners
- Medical professionals
- Malaysians with mortgages
- Malaysians with too many insurance policies
- Malaysians earning Singapore dollars
- Malaysians working in the Middle East
- Malaysians working in the US or Europe
- Malaysians with overseas property
Not sure? Start with a confidential assessment and I’ll tell you which roadmap applies.
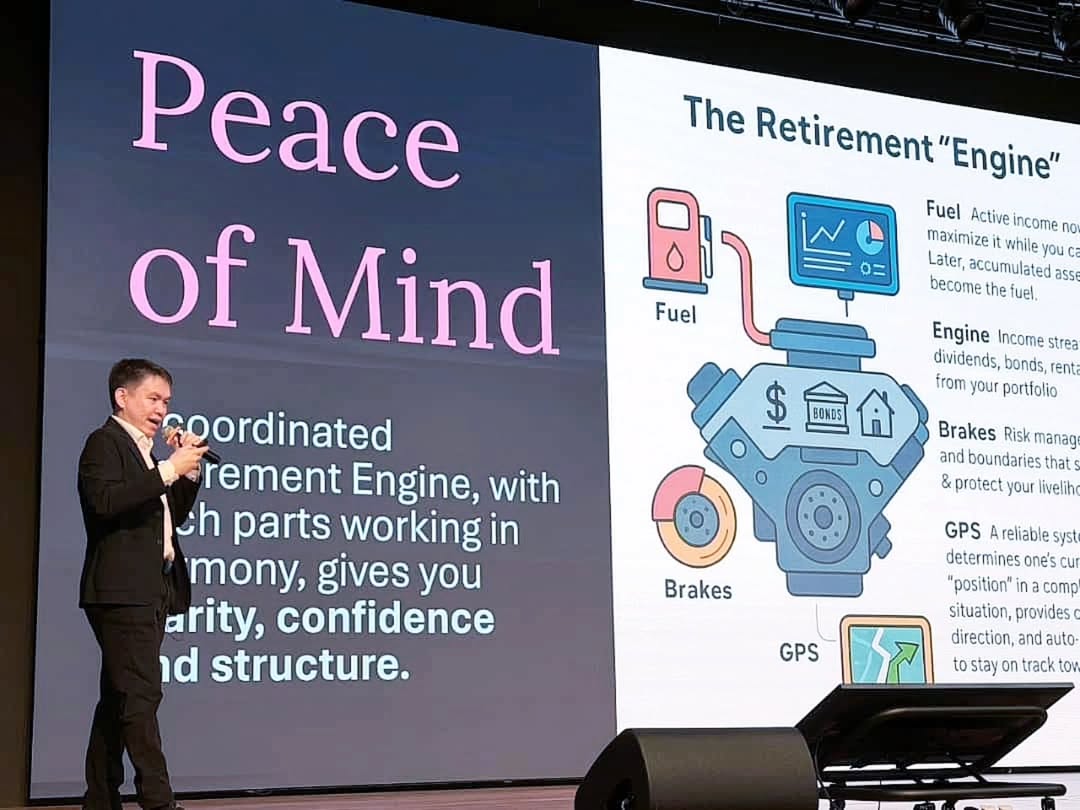
I am CF Lieu, My work includes being a licensed advisor for my retirement financial advisory clients and trainer for financial institutions and banks since 2012.
Retirement Financial Advisor for Malaysians with Investment Properties
“My properties are my retirement plan” is one of the most common sentences I hear from Malaysian professionals – and one of the most expensive to leave unexamined. Property has served many Malaysian families well. But a retirement plan built on two or three leveraged residential units has a specific set of risks that only become visible when the salary stops and the plan has to perform on its own.
A retirement financial advisor for property investors helps answer the questions the property itself can’t: what these units will actually yield net of costs and vacancies, whether the loans should survive into retirement, how concentrated the household really is, and whether – and when – some of it should be sold.
Why a property-heavy portfolio needs a different planning process
The first issue is yield reality. Malaysian residential rental yields are often modest once you subtract maintenance, sinking fund, assessment, quit rent, agent fees, vacancy periods and the inevitable repairs – and the net figure is frequently lower than the owner assumes, because the calculation was never done. The property rental for retirement question has to be answered with real numbers, not gross rent divided by purchase price.
The second is leverage. A mortgage on an investment property is a reasonable tool during a high-income career. Carrying that same loan into retirement, funded by rental that may not cover it, is a different proposition entirely. The question of whether to pay down the mortgage or invest changes its answer as retirement approaches.
The third is liquidity and concentration. Property is lumpy, slow to sell, and – for most Malaysian investors – concentrated in one country, one asset class, and often one city. A retirement plan needs to be able to produce cash reliably; a portfolio of three condos in the same township cannot promise that.
What a financial advisor for property investors should help clarify
The first task is to compute the true contribution of each property to retirement income: net yield after all costs, expected vacancy, capital expenditure over a 20-year holding period, and the loan position. This often reveals that a property the owner regards as an asset is, in retirement terms, close to neutral.
The second is to compare that against alternatives. If the equity locked in a unit could produce more reliable retirement income invested elsewhere – with less management and more liquidity – that is a decision worth making deliberately. My guide to investment options in Malaysia and the dividend-investing approach show what the alternatives look like.
The third is sequencing. Which unit to sell, when, in what order, and how the proceeds are deployed – these decisions have tax, timing and market implications that reward planning years in advance rather than a forced sale at the wrong moment.
The decisions that need coordination
- Hold, sell, or refinance – per unit. Each property should earn its place on its own numbers. A retirement plan is not obliged to keep a unit because it was bought.
- Debt into retirement. Decide explicitly whether any investment loan should still exist at the retirement date, and what happens if rental income drops while the loan doesn’t. The DSR discipline used in property investing still applies — to a retiree with no salary.
- Concentration. Property, EPF and a Malaysian employer already put most Malaysians heavily in one economy. A retirement portfolio needs balance beyond bricks.
- Cash reserves. Property produces no emergency liquidity. A retiree living on rental income needs structured cash reserves sized for vacancies and repairs, not just market downturns.
- Estate simplicity. Multiple properties across multiple names create succession complexity. It is easier to plan the estate while the owner can still make the decisions.
A better way to evaluate your current position
What a property investor needs is not another opinion on the market, but a model: every unit’s net cash flow, loan balance and equity, alongside the rest of the retirement balance sheet, run against scenarios – a prolonged vacancy, a rate rise, a 20% price fall, a sale in year 5 versus year 12. The AI-powered scenario analysis on this page uses the same engine I use with advisory clients to show, in numbers, whether “my properties are my retirement plan” actually holds – and what changes if it doesn’t.
A typical situation I see
A couple in their early 50s, three residential units bought between 2009 and 2016, combined gross rent of RM9,800 a month, two loans still running with RM1.1 million outstanding, and a firm belief that the rental will fund retirement at 58. Modelled properly – net of loan instalments, maintenance, sinking fund, tax and a realistic 8% vacancy – the three units contribute roughly RM2,600 a month, not RM9,800, until the loans are cleared. The plan works, but only if one unit is sold in the next three years to clear the debt on the other two, and the proceeds are invested for income rather than in a fourth property. That is not what the couple expected to hear, but it is what the numbers say – and it is far better heard at 52 than discovered at 60.
Frequently asked questions
Is rental income a reliable retirement income source in Malaysia?
It can be one component, but rarely the whole answer. Net yields after all costs are usually well below the gross figure, vacancies are lumpy, and property produces no liquidity in an emergency. A retirement plan needs rental income to be one leg of a diversified structure.
Should I keep investment property loans into retirement?
Generally no, unless the net rental comfortably covers the instalment with a margin for vacancy and rate rises. A retiree without salary income has no buffer if the tenant leaves. Model the loan into retirement explicitly before deciding.
When is the right time to sell an investment property before retiring?
Early enough that the sale is a choice, not a necessity – typically three to seven years before the retirement date. This allows the sale to be timed to market conditions and the proceeds to be deployed into income-producing assets before they are needed.
How to choose an advisor without adding another conflict
Property investors are surrounded by advice from people who earn when a transaction happens: agents, developers, mortgage brokers. Choose an advisor who has no stake in whether you buy, sell or hold – licensed, fee-only, and willing to tell you that a property you love isn’t pulling its weight. My guide on choosing a certified financial planner in Malaysia sets out what to check.